In the Laurentides, your roof is one of the first things a home insurer looks at, and winter is when it gets tested hardest. Most home policies in Quebec cover sudden, accidental roof damage, such as a collapse under the weight of snow or a leak caused by a storm, but they generally exclude damage that comes from wear and tear, poor maintenance or slow deterioration. This guide explains how roof age and material affect your insurability, how ice dams and snow load claims are usually handled, and what you can do now to protect both your house and your coverage.
Key takeaways
- Roof age and material matter to insurers. An older or poorly maintained roof can mean higher premiums, a higher deductible, depreciated payouts on roof claims, or difficulty finding coverage at all.
- Sudden vs gradual is the line that decides most claims. A roof that collapses under heavy snow is treated very differently from a roof that leaked slowly for years.
- Ice dam water damage is a grey zone. Coverage depends on your policy wording, especially for water entering through the roof. Read the water damage section and ask your broker or insurer to explain it in writing if needed.
- Documentation is your best defence. Keep invoices, photos and dates for roof replacement, repairs, inspections and snow removal.
- Known changes must be declared. Under the Quebec Civil Code, you must answer your insurer’s questions truthfully and notify it of changes that increase the risk.
- Call a roofer early, not after the collapse. Signs like sagging ceilings, sticking interior doors, new cracks in walls or unusual creaking are warnings, not quirks.
Why roofs matter so much to insurers in the Laurentides
The Laurentides combine heavy snowfall, frequent freeze-thaw cycles, long winters and a large stock of older houses and chalets. From Saint-Jérôme and Mirabel to Sainte-Adèle, Val-David, Mont-Tremblant and Mont-Laurier, many homes sit on wooded lots where branches, shade and slow melting all add stress to the roof. Insurers know that a roof failure can trigger a chain of losses: water in the attic, damaged insulation, wet drywall, mould, ruined contents and sometimes a family that has to move out during repairs.
That is why most home insurance applications in Quebec include questions about the roof: its age, the type of covering, the date of the last replacement, and sometimes whether it has been inspected recently. If you are comparing quotes, our guide on how to shop for home insurance in the Laurentides explains how to prepare these answers in advance so each insurer is quoting on the same information.
How roof age and material affect insurability
Insurers do not all use the same rules, and none of them publish a universal age limit, so you should not assume a fixed cut-off. What is consistent is the logic: the older a roof is relative to its expected life, the more likely it is to leak, and the more expensive a claim tends to be.
Roof age
When you apply, expect to be asked the year the roof covering was last replaced. Depending on the insurer and the age you declare, possible outcomes include:
- A standard quote with no special conditions.
- A request for photos, an inspection report or proof of replacement (invoice from the roofer).
- A higher deductible that applies specifically to roof or water damage.
- Settlement of roof claims on an actual cash value basis (with depreciation) rather than full replacement cost.
- A condition that the roof be replaced within a set period, or a refusal to offer coverage.
If you do not know the age of your roof, say so rather than guessing. A guess that turns out to be wrong can become a problem at claim time. Your home inspection report, the seller’s declaration, or old invoices are good places to find the answer.
Roof material
Common roof coverings in the region include asphalt shingles, steel or metal roofing, and multi-layer or membrane systems (such as elastomeric membranes) on flat or low-slope roofs. Cedar shingles still appear on some older houses and chalets. Each material ages differently and reacts differently to snow, ice and wind. Insurers generally consider the type of covering together with its age and condition. What you should do is describe the material accurately on your application and keep proof of what was installed and when.
| Roof factor |
Why insurers care |
What you can provide |
| Age of covering |
Older coverings are more likely to leak or fail |
Roofer’s invoice, permit, seller’s declaration |
| Material |
Different durability and resistance to ice and wind |
Invoice or product specification |
| Slope (pitched vs flat) |
Flat roofs hold snow and water differently |
Inspection report, photos |
| Condition |
Missing shingles, curling, blistered membranes signal risk |
Recent inspection report, dated photos |
| Attic ventilation and insulation |
Linked to ice dams and condensation |
Inspection notes, upgrade invoices |
| Maintenance history |
Shows the risk is being managed |
Snow removal receipts, repair invoices |
Ice dams: what they are and how insurers see them
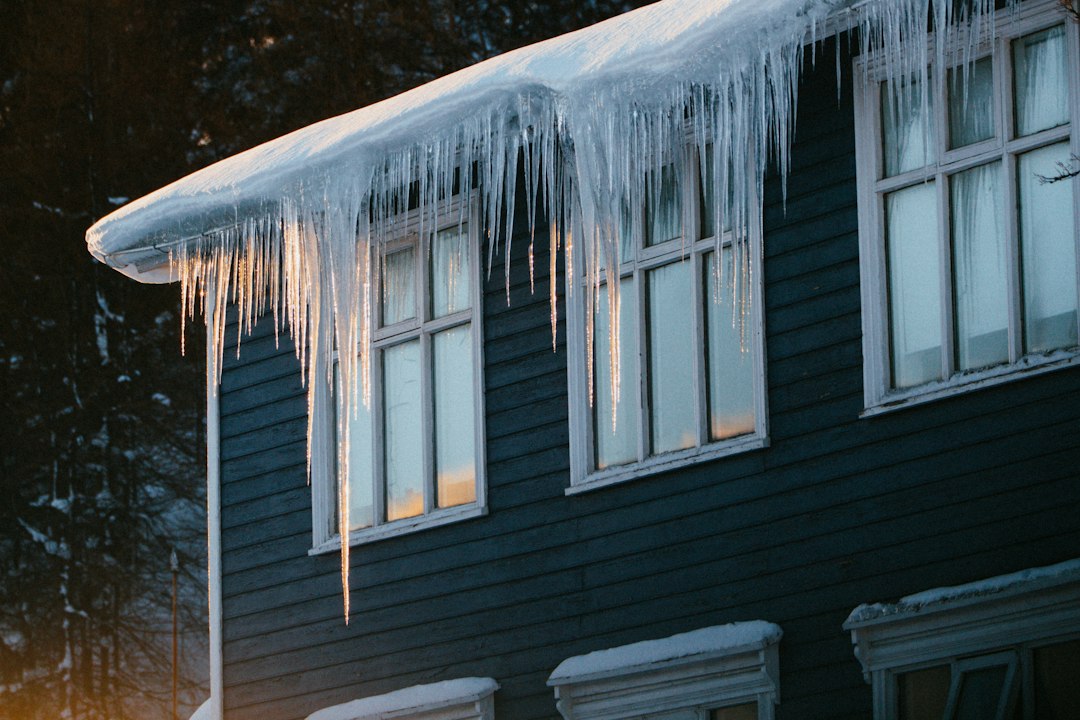
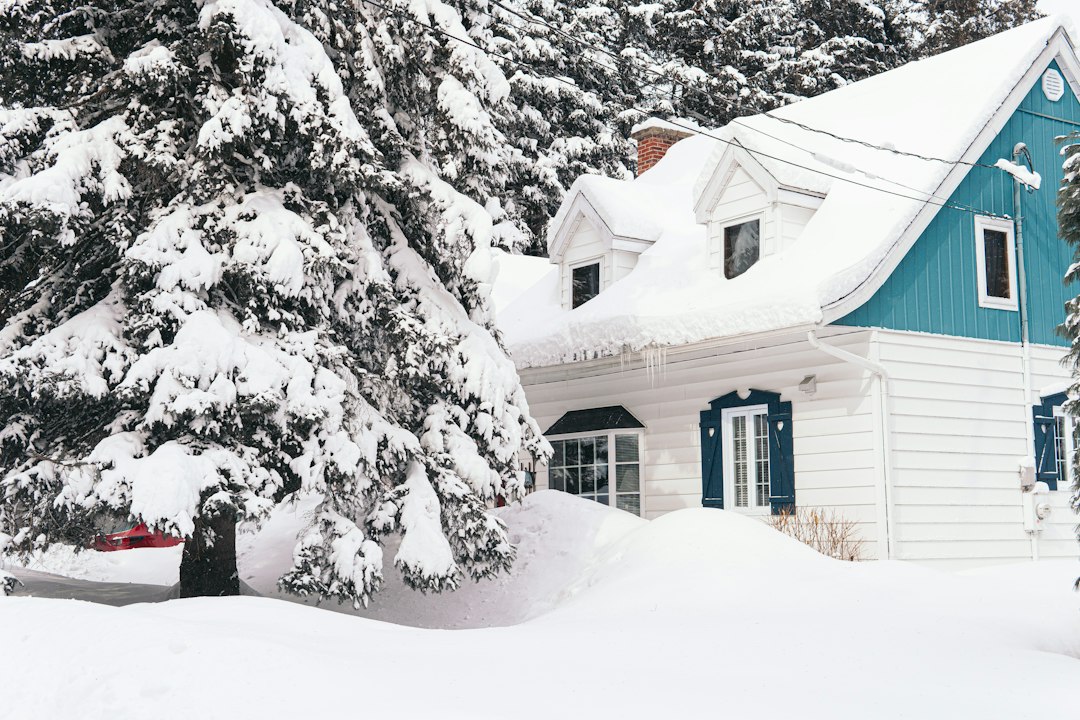
An ice dam forms when heat escaping from the house warms the roof deck, snow melts higher up, and the water refreezes at the colder eaves. The ridge of ice traps more meltwater behind it, which can back up under shingles and drip into the attic, walls or ceilings. Long icicles along the edge of the roof are often a visible clue.
The main causes are usually inside the house rather than outside: insufficient attic insulation, air leaks from the living space into the attic, poor ventilation, or heat sources such as recessed lights and uninsulated ducts. That matters for insurance, because an insurer may view repeated ice dams as a maintenance or construction issue rather than a sudden event.
Is ice dam damage covered?
There is no single answer for Quebec, because coverage depends on the exact wording of your policy. In general terms:
- Some policies, particularly broad or “all risks” forms, may cover sudden and accidental water damage from ice dams to the interior of the home, subject to your deductible and exclusions.
- Many policies distinguish between water that enters through the roof and water that escapes from plumbing, and may treat them differently.
- Damage to the roof covering itself caused by gradual ice build-up may be treated as wear and tear or lack of maintenance.
- Repeated, known ice dam problems that were never corrected can weaken your position on a claim.
Water damage is the single biggest source of confusion for homeowners. Our detailed guide on water damage, sewer backup and flood insurance in the Laurentides explains how these water categories and endorsements usually work.
Key tip: Ask your broker or insurer a precise question: “If an ice dam causes water to enter through my roof and damage my ceilings, is that covered under my policy, and what deductible applies?” Ask for the answer in writing, by email, so you have it on file.
Preventing ice dams
- Have the attic insulation and ventilation evaluated, ideally during a calm season.
- Seal air leaks between the living space and the attic (light fixtures, attic hatches, plumbing stacks).
- Keep gutters and downspouts clear before winter.
- Remove snow from the lower part of the roof safely, using a roof rake from the ground or a professional service.
- Do not chip ice with axes or hammers; you can damage the covering and void manufacturer warranties.
Snow load and roof collapse
Heavy snow is part of life in the Laurentides, but snow becomes dangerous when it accumulates, gets wet, or is topped by rain that soaks in and adds weight. Drifts on the lee side of a roof, snow sliding from a higher roof onto a lower one, and ice build-up can all concentrate load in specific areas. Flat roofs, low-slope additions, carports, garages, sheds and older outbuildings are particularly exposed.
Warning signs of excessive snow load
Quebec’s building authority, the Régie du bâtiment du Québec (RBQ), regularly reminds owners to watch for warning signs that a roof is carrying too much snow, including:
- Cracks appearing in interior walls.
- Interior doors that stick or rub against their frames.
- Unusual creaking or cracking sounds.
- Ceilings that sag or warp.
If you notice these signs, the RBQ’s advice is to have the roof cleared, even if the amount of snow does not look dramatic, and to use specialized companies with the right equipment so the waterproof membrane is not damaged. The Quebec government also publishes seasonal reminders on Québec.ca about safe snow and ice removal from roofs.
Is snow load collapse covered?
Many Quebec home policies cover the collapse of a building caused by the weight of snow, ice or water as a sudden and accidental event, subject to the wording of the policy, your deductible and any exclusions. However, the details matter:
- Outbuildings: Detached garages, sheds and carports are often covered under a separate section with lower limits. Temporary shelters (such as fabric car shelters) may be limited or excluded.
- Neglect: If an insurer can show that a structure had obvious defects, rot or prior damage that was ignored, it may argue that the loss stems from deterioration rather than a sudden event.
- Vacant or seasonal homes: Chalets left unoccupied for long periods may carry conditions about inspections and winter maintenance. See our guide to chalet and cottage insurance in the Laurentides for the typical requirements.
- Contents and living expenses: Damaged furniture and the cost of living elsewhere during repairs fall under other parts of the policy, each with their own limits.
What is generally covered and what is not
Every policy is different, but the following table summarizes how insurers typically approach winter roof situations. Use it as a starting point for a conversation with your broker, not as a guarantee.
| Situation |
Often covered? |
Common conditions or exclusions |
| Roof collapses under sudden heavy snow load |
Often, as sudden and accidental damage |
Deductible; exclusions for pre-existing defects or neglect |
| Wind tears off shingles during a storm |
Often |
Older roofs may be settled at depreciated value |
| Tree falls on roof during a storm |
Often |
Removal costs may have limits; dead trees you ignored may complicate the claim |
| Interior water damage from an ice dam |
Depends on policy wording |
May require a specific form or endorsement; deductibles may differ |
| Roof covering worn out after many years |
Generally not |
Wear and tear and lack of maintenance are standard exclusions |
| Slow leak that caused rot or mould over months |
Generally not |
Gradual damage and repeated seepage are commonly excluded |
| Damage caused during snow removal by you or a contractor |
Varies |
May be the contractor’s liability; check their insurance |
Wear and tear vs sudden damage: the distinction that decides claims
Home insurance is designed to cover unexpected events, not the normal ageing of a building. A roof that reaches the end of its life and starts to leak is, from an insurer’s point of view, a maintenance expense. A roof that is damaged by a storm, a falling tree or a sudden collapse is an insurable event.
In practice, many winter claims involve both. A storm may tear off shingles that were already curling and brittle. An adjuster will look at the age and condition of the roof, the weather on the date of loss, and any signs of previous leaks such as old water stains or rotted decking. This is where your records become important: dated photos, inspection reports and invoices can show that the roof was in reasonable condition before the event.
Your legal duties under Quebec law
The Civil Code of Québec places specific obligations on policyholders:
- Duty to declare the risk: When you apply, you must disclose the facts you know that are likely to materially influence the insurer’s decision to accept the risk or set the premium. Answering roof questions accurately is part of that duty.
- Aggravation of risk: During the policy, you must promptly notify your insurer of changes within your control that increase the risk in a material way. Major renovations or a change in how the home is used are typical examples. If you are unsure whether something counts, ask.
- Notice of loss: You must notify the insurer of a loss as soon as you become aware of it.
Misrepresentation or failure to declare can lead to a reduced indemnity or, in cases of fraud or serious omissions, to the policy being cancelled. The safest approach is simple: answer every question honestly, and if you are not sure, say so.
Maintenance documentation: build your roof file
A simple roof file can save a lot of trouble at renewal time and during a claim. Keep it in a folder or a cloud drive, and add to it every year.
- Proof of installation: The roofer’s invoice showing date, material and scope of work. Include the municipal permit if one was issued.
- Warranty documents: Manufacturer and contractor warranties, with any maintenance conditions they impose.
- Inspection reports: Pre-purchase inspection report and any later roof inspections.
- Seasonal photos: Dated photos of the roof each fall and spring, plus photos of the attic if you can access it safely.
- Snow removal records: Contracts or receipts from snow removal services, with dates.
- Repairs: Invoices for any repairs, flashing work, venting changes or insulation upgrades.
- Correspondence: Emails with your insurer or broker about the roof.
When you buy a property, start this file on day one. Our home insurance checklist for buying a property in the Laurentides lists the roof information insurers usually ask for before closing.
When to call a roofer
Do not wait for a leak to find a roofing professional. Ideally, have a contractor you trust before winter arrives, because demand spikes after major storms. Consider calling a roofer when:
- Your insurer or lender asks for a roof inspection or proof of condition.
- You see missing, curled, cracked or granule-shedding shingles.
- Flashing around chimneys, skylights or vents looks loose or rusted.
- You notice stains on ceilings, damp insulation or frost build-up in the attic.
- Ice dams form every winter in the same places.
- The roof is approaching the end of its expected life and you want to plan replacement before an insurer imposes conditions.
- Heavy snow or ice has accumulated and you see any of the RBQ warning signs listed above.
To compare local contractors serving Saint-Jérôme, Saint-Sauveur, Sainte-Agathe-des-Monts, Mont-Tremblant and the rest of the region, browse our partner directory of Laurentides roofing contractors. Ask any contractor for a written quote, proof of their RBQ licence, and proof of their own liability insurance before work begins.
Key tip: Before you sign a roof replacement contract, call your insurer or broker. Some insurers adjust the premium or remove conditions once a new roof is installed, and they will want the invoice. A new roof can also be a good moment to review your whole policy.
Safe snow removal: protect yourself and your coverage
Roof snow removal is dangerous. Falls from roofs and ladders cause serious injuries every winter in Quebec. For most homeowners, the safest options are a roof rake used from the ground for the lower edge, or a professional service with proper fall protection.
If you hire a service:
- Ask whether the company carries liability insurance and request proof.
- Agree in writing on what is included (main roof, garage, balconies, ice removal at the eaves).
- Ask that tools be used in a way that does not damage shingles, membranes or flashing.
- Keep the receipt with the date, and take before-and-after photos.
If a contractor damages your roof while removing snow, the first step is usually to notify the contractor and their insurer. Let your own insurer know as well, because a leak can develop later.
Chalets, rentals and secondary homes
Secondary homes in the Laurentides face extra winter risk because nobody may be on site when snow piles up or an ice dam starts leaking. Insurers often add conditions for seasonal or unoccupied properties, such as regular visits during winter, minimum heating, or water shut-off when the property is empty. If you rent your chalet to guests, the insurer will also want to know, because rental use changes the risk. Our guide to short-term rental chalet insurance in Quebec explains why you must declare it.
A practical solution is to arrange a winter maintenance contract with a local roofer or caretaker who can check the roof after major storms. Many owners combine this with a seasonal inspection from one of the roofing specialists listed on toiture.thelaurentides.com. If you are still looking for a property, the regional portal chalets.thelaurentides.com can help you compare chalet options.
If winter damage happens: what to do first
- Make sure everyone is safe. If the ceiling is sagging or you hear cracking, leave the area and call emergency services if needed.
- Prevent further damage. Move belongings, place buckets, shut off electricity to wet areas if safe, and arrange emergency tarping or snow removal.
- Document everything. Take photos and videos before cleanup, and keep receipts for emergency work.
- Notify your insurer promptly. Call the claims line as soon as you are aware of the loss.
- Do not throw away damaged materials until the adjuster has seen them or approved disposal.
Our step-by-step guide on how to file a home insurance claim in Quebec covers the full process, including adjusters, additional living expenses and what to do if you disagree with the insurer’s decision.
Frequently asked questions
Will my insurer refuse to cover my home because the roof is old?
Some insurers may, but practices vary. Others may offer coverage with conditions, such as a higher deductible, depreciated settlement of roof claims, or a requirement to replace the roof within a given period. Shopping with a broker or comparing several insurers can help if one declines.
Is roof snow removal mandatory for my insurance?
Policies rarely state a specific snow depth, but you are generally expected to maintain your property reasonably. If a collapse happens on a structure you knew was overloaded and did nothing about, the insurer may question the claim. For chalets and vacant homes, written conditions about winter visits are common, so read your policy.
Does home insurance pay for a new roof when mine wears out?
No. Normal wear and tear and end-of-life replacement are maintenance costs. Insurance generally responds only to sudden, accidental damage, such as storm damage or a collapse.
Are icicles and ice dams my responsibility?
Yes, as the owner you are responsible for maintaining your property. Falling ice can also injure passersby or damage vehicles, which may become a liability issue. Removing dangerous icicles safely, or hiring someone to do it, protects others and your coverage.
Should I tell my insurer when I replace my roof?
Yes. A new roof is generally good news for the insurer and may improve your terms. Send the invoice showing the date and material, and ask whether your premium or conditions change.
My garage roof collapsed but the house is fine. Is that covered?
Detached buildings are usually covered under a separate section of the policy, often with a limit expressed as a percentage of the dwelling amount or a fixed amount. Check that section, and notify your insurer promptly with photos.
Want a second opinion on your coverage? Contact us and we will point you in the right direction.
This article is for general information only and is not insurance advice. Always confirm details with a licensed broker or your insurer.